

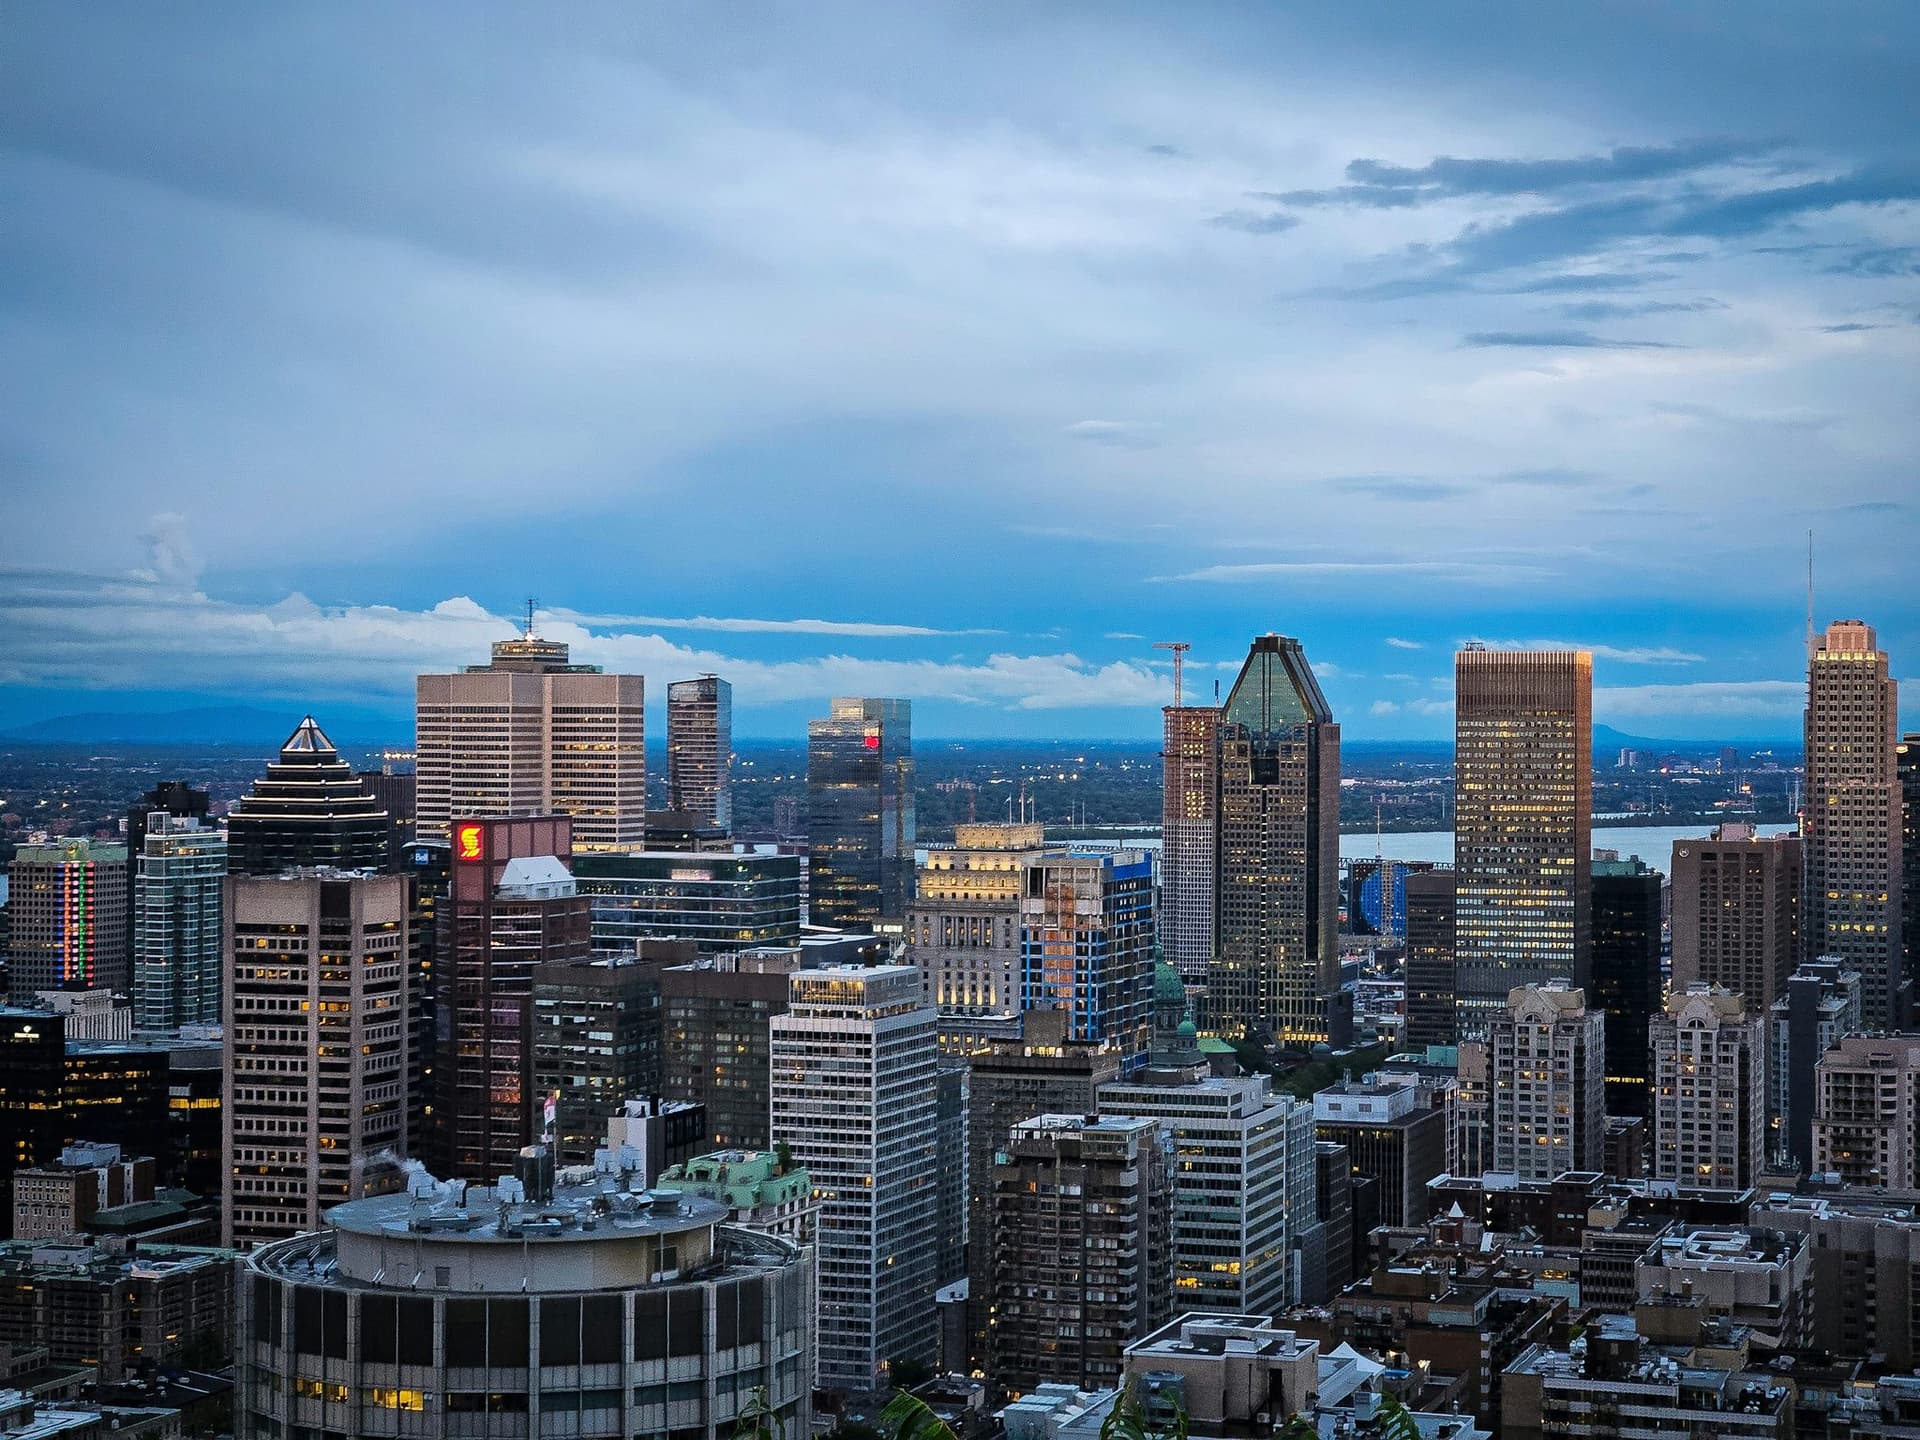
Montreal, QC
The Canadian housing market entered spring with less momentum than many had expected, but also with more stability than it had a year ago. After January’s pullback, February brought another modest decline in sales activity, while inventory held near long-run norms and prices continued to ease rather than break sharply in either direction. The result is a market that still feels restrained, but increasingly grounded.
In that sense, the latest data builds naturally on the trend that emerged in the previous update. March’s story was about a market cooling as inventory rebuilt and conditions moved. Early April’s story is that the cooling has continued, but so has the move toward more balanced conditions. According to the Canadian Real Estate Association, national home sales edged down another 1.3% from January to February on a seasonally adjusted basis, marking a fourth straight monthly decline. New listings, which had jumped in January, fell back 3.9% in February. Months of inventory ended February at five, unchanged from January and broadly in line with the long-term national average.

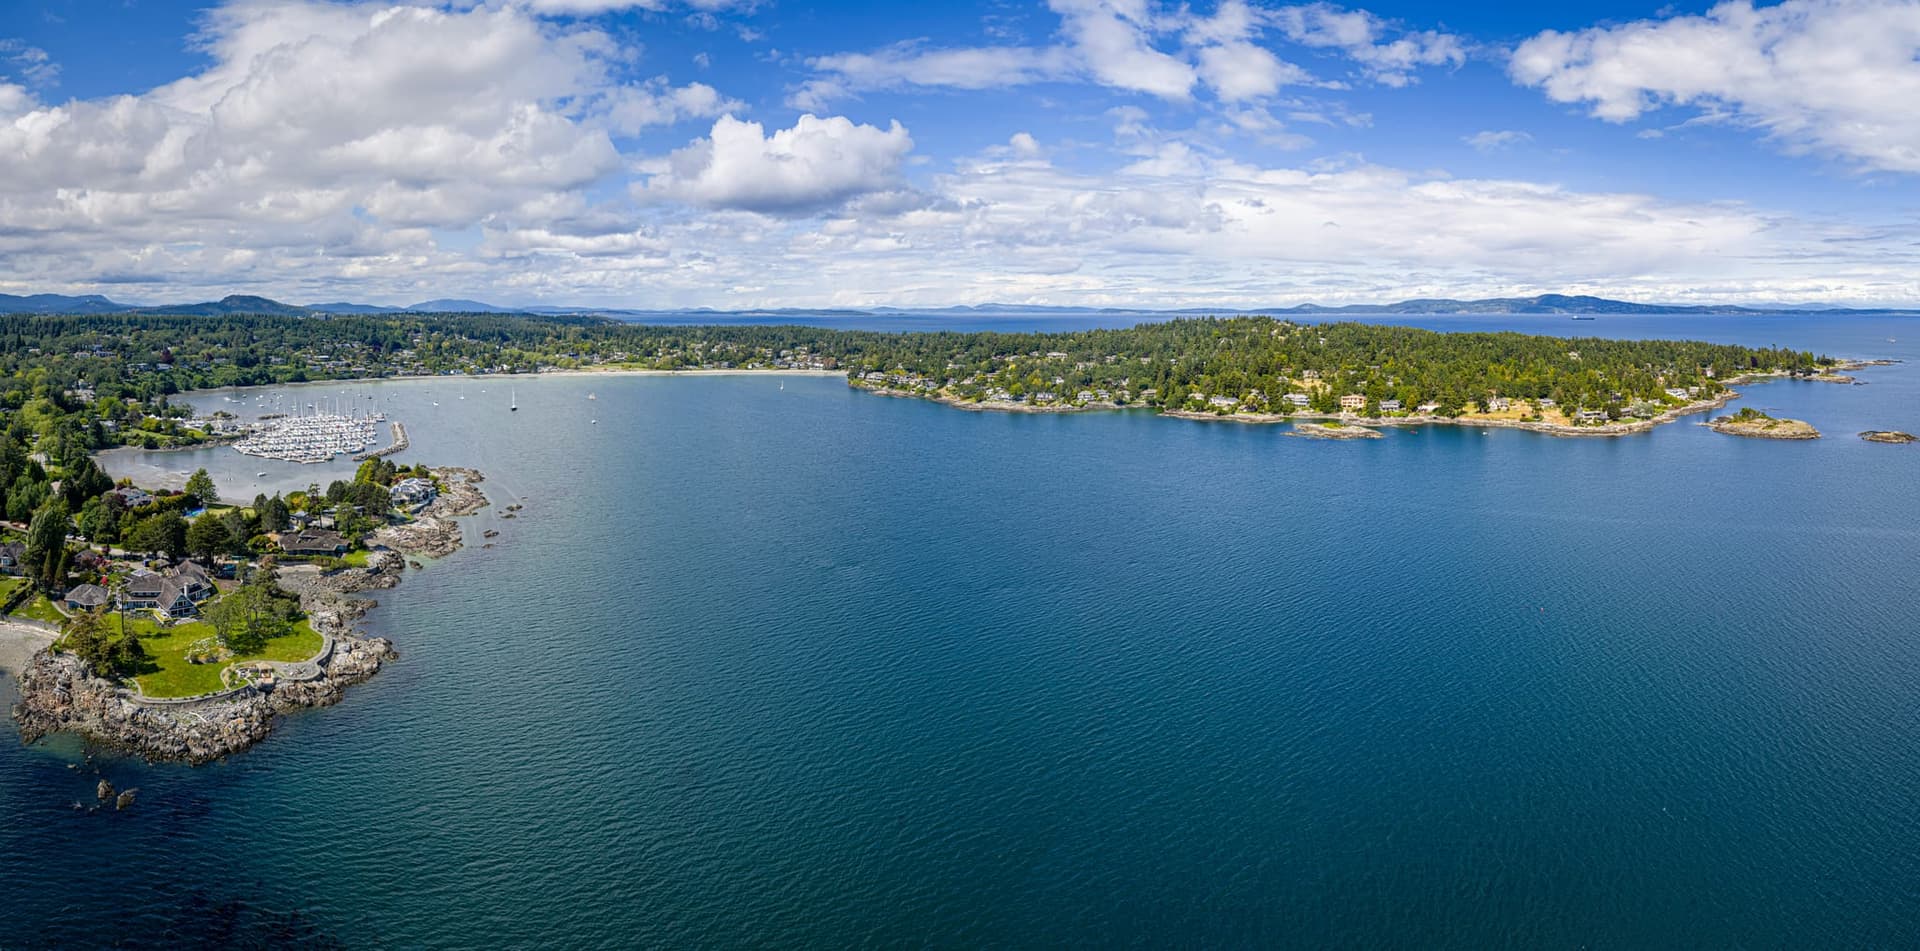
Saanich, BC
Prices are also sending a clearer signal now than they were at the start of the year. The national average sale price came in at $663,828 in February, essentially flat from a year earlier, down just 0.2%. But the more useful measure is the benchmark-based MLS® Home Price Index, which strips out some of the distortion caused by changes in what is selling. That index fell 0.6% month over month in February and was down 4.8% from a year earlier, suggesting that softness remains present even if headline averages look steady.
SUBSCRIBE TO THE HAVEN MAILING LIST
Curated homes, market intelligence and design stories — a few emails a month.
No spam. Unsubscribe any time.
A flat national average price can make the market appear more stable than it feels on the ground, particularly in regions where benchmark prices are still slipping. CREA noted that year-over-year prices remained down in British Columbia, Alberta, and Ontario in February, offsetting gains elsewhere. So while the national market is no longer in the kind of broad correction seen earlier in the cycle, it is also not in a uniform recovery. The spring market is arriving unevenly.
Supply, meanwhile, is improving, though not without complications. On the resale side, the market is sitting close to balanced territory nationally. On the construction side, February housing starts rose 4.5% from January to a seasonally adjusted annual rate of 250,900 units, while the six-month trend measure was essentially flat at 256,005. Actual starts in centres with populations above 10,000 were up 10% year over year in February, even as some major urban markets, including Toronto, remained comparatively weak.
That construction story is more nuanced than a simple supply win. CMHC’s Spring 2026 Housing Supply Report noted that housing starts rose 6% in 2025, helped by record rental construction and more missing-middle development. But it also flagged a weaker pipeline for ownership-oriented housing, particularly in Toronto and Vancouver, where condominium presales have fallen, unsold inventory has risen, and tighter financing conditions are weighing on future projects. In other words, more supply is being added, but not always in the segments or locations where ownership demand is likely to return first.

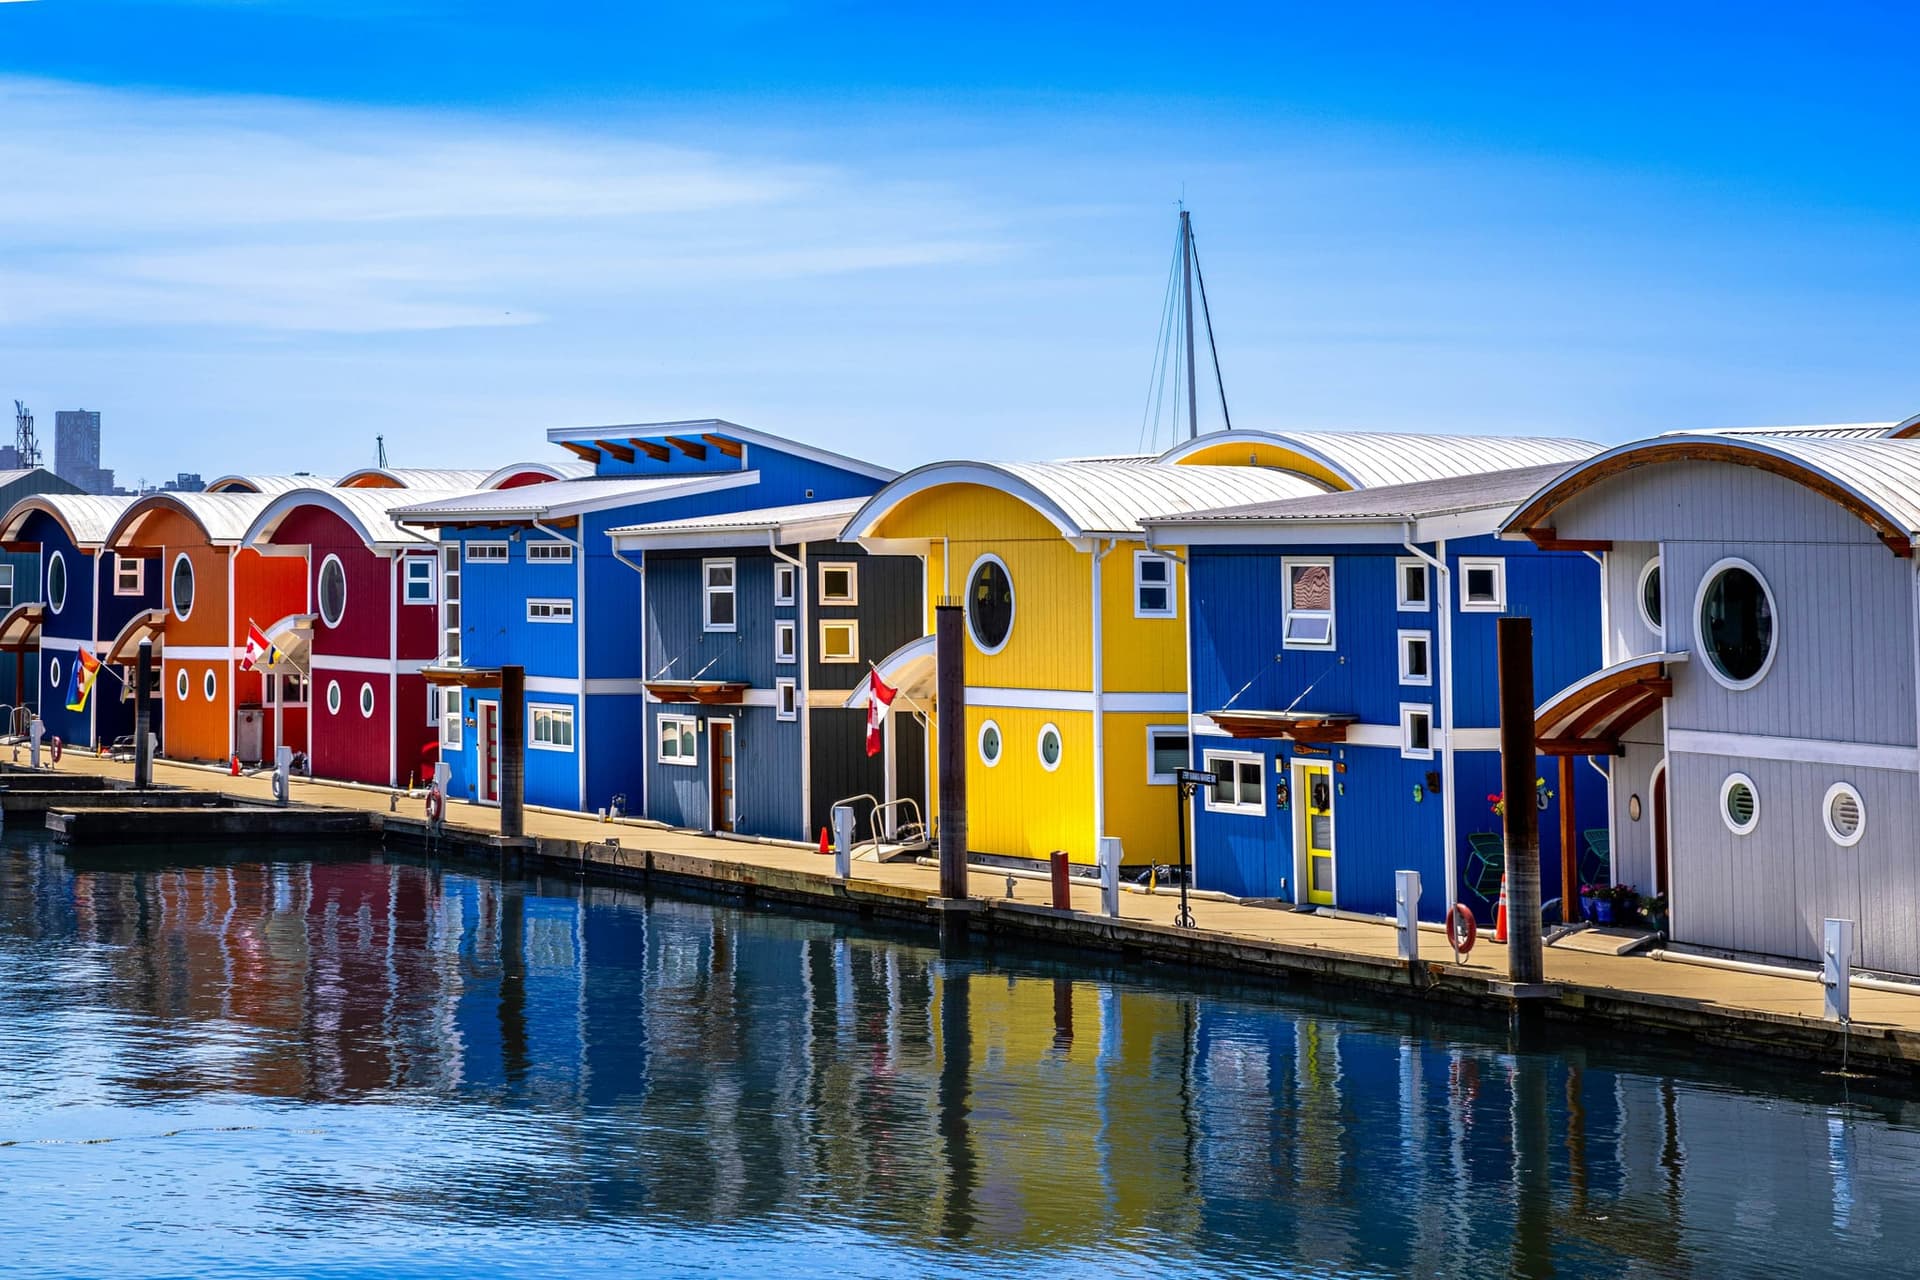
North Vancouver, BC
Interest rates remain central to that demand question. On March 18, the Bank of Canada held its target for the overnight rate at 2.25%, leaving borrowing costs unchanged as policymakers assessed a more uncertain global backdrop. That decision did not give buyers the fresh rate-cut signal some had been waiting for, and it helps explain why activity has remained subdued even as market conditions have become less frenzied. The affordability picture has improved from its most strained period, but it has not improved enough to unlock a broad-based rebound yet.
For now, that leaves Canada in a more measured spring market than the one many forecasters had anticipated at the start of the year. CREA’s January outlook still called for a 5.1% rise in national home sales in 2026, led largely by British Columbia and Ontario, where activity has more room to recover. But as of early April, the latest hard data suggests that recovery is still waiting for stronger follow-through. What the market has achieved so far is not a clear upswing, but something quieter: a little more inventory, somewhat softer pricing, and conditions that look less distorted than they did a year ago.
That may not make for an especially dramatic spring, but it does make for a more settled one. Buyers are still selective. Sellers are operating in a market with more competition and less urgency than during the pandemic boom. And nationally, housing is looking less like a market in transition and more like one that is gradually finding its level.












