
Vancouver, BC
Canada’s housing market entered the year with expectations for a modest rebound. However, at this point, that recovery is looking slower, more uneven, and more conditional than many early-year forecasts had suggested.
The latest data from the Canadian Real Estate Association shows a spring market that is moving, but not breaking out. National home sales edged up 0.7% from March to April, while actual monthly activity was still 4% below April 2025. Prices also remained mixed: the MLS® Home Price Index slipped 0.1% month over month and was down 4.2% from a year earlier, while the national average sale price rose 2.2% year over year to $695,412.
Québec, QC
The national average sale price can move higher when a larger share of activity happens in more expensive markets, so it does not necessarily mean prices are strengthening across the country. CREA’s MLS® Home Price Index, which is designed to track price changes more consistently, still shows values below last year’s levels. Even so, the April decline was the smallest monthly drop since October 2025, suggesting that price stabilization is starting to take shape.
SUBSCRIBE TO THE HAVEN MAILING LIST
Curated homes, market intelligence and design stories — a few emails a month.
No spam. Unsubscribe any time.
The modest April improvement does not erase the softer start to the year. In mid-April, CREA downgraded its resale housing forecast, citing weaker-than-expected first-quarter activity, economic uncertainty, and higher fixed mortgage rates tied to rising bond yields. CREA now expects 474,972 homes to trade through Canadian MLS® Systems in 2026, up just 1% from 2025. The national average home price is forecast to rise 1.5% to $688,955.
Banff, AB
That forecast is modest on the surface, but the regional differences underneath it is more telling. CREA expects virtually no average price growth in British Columbia, Alberta, and Ontario, while other provinces are expected to post gains in the 2% to 5% range. In other words, the national market may look relatively stable by year-end, but that stability is likely to come from stronger provinces offsetting weaker large markets rather than from a broad-based rebound.
The spring market is also being shaped by a rate environment that remains difficult for buyers to read. The Bank of Canada held its policy rate at 2.25% on April 29, keeping variable-rate relief limited for now. At the same time, fixed mortgage rates have been affected by higher bond yields, leaving buyers who had been waiting for lower borrowing costs with a less straightforward decision. The market is not back in a rising-rate shock, but financing costs are still high enough to keep affordability at the center of buyer decisions.
Calgary, AB
Supply is not moving in one simple direction either. New listings jumped 4.1% month over month in April as the spring market began to take shape, while sales rose more modestly. That pushed the national sales-to-new-listings ratio down to 45.6%, near the low end of what CREA considers balanced market territory. Active listings reached 187,647 at the end of April, up 2.2% from a year earlier but still 6.1% below the long-term average for that part of the year. Months of inventory rose to 5.2, close to the long-term national average of five.
Those figures point to a market with more room for comparison, but not a nationally oversupplied one. Buyers have more choice than they did during the tightest periods of the past few years, and they are less likely to move quickly unless pricing, location, and property condition line up. Sellers, meanwhile, are dealing with a market where demand exists but urgency is limited. Well-priced homes can still move, but the market is less forgiving of ambitious asking prices, especially in areas where inventory has rebuilt.
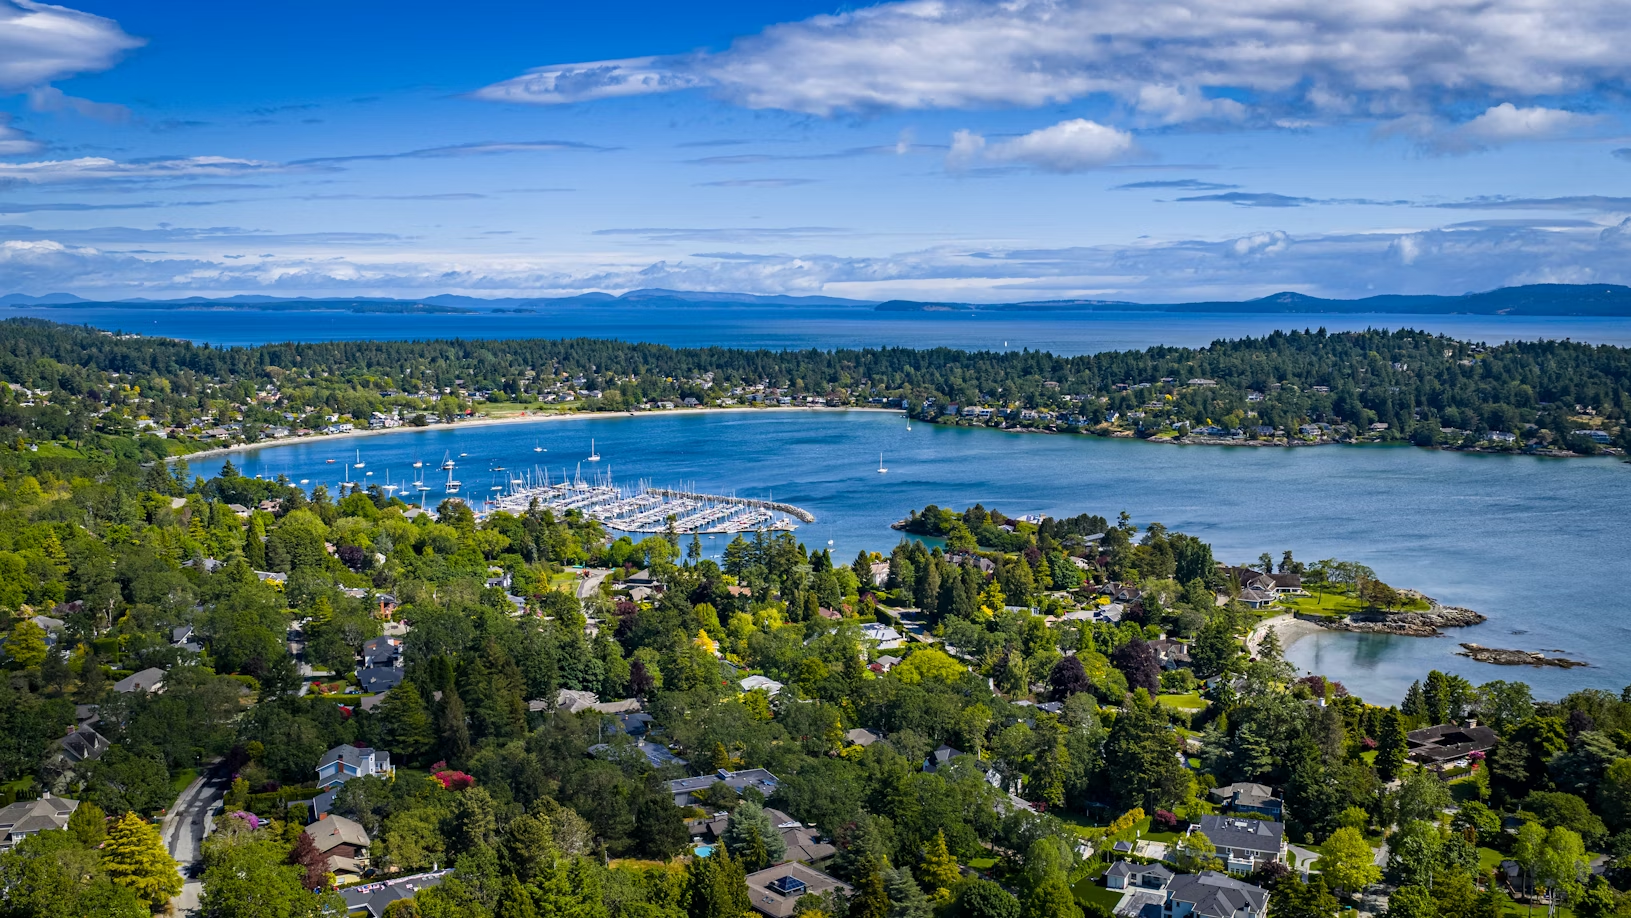
Saanich, BC
Canada’s rental market is adding a second storyline. According to CMHC’s 2026 Housing Market Outlook, rental markets are moving closer to balance nationally as new rental supply arrives and demand cools with slower population growth. Purpose-built rental construction is expected to remain the main driver of housing starts, even as overall construction activity slows.
Private rental data shows that pressure is already showing up in asking rents. Rentals.ca and Urbanation reported that average asking rent across Canada fell to $2,027 in April, down 4.7% from a year earlier and marking the 19th consecutive month of annual rent declines. Purpose-built apartment rents were down 3.7% year over year, while condo apartment rents fell 5.6%.
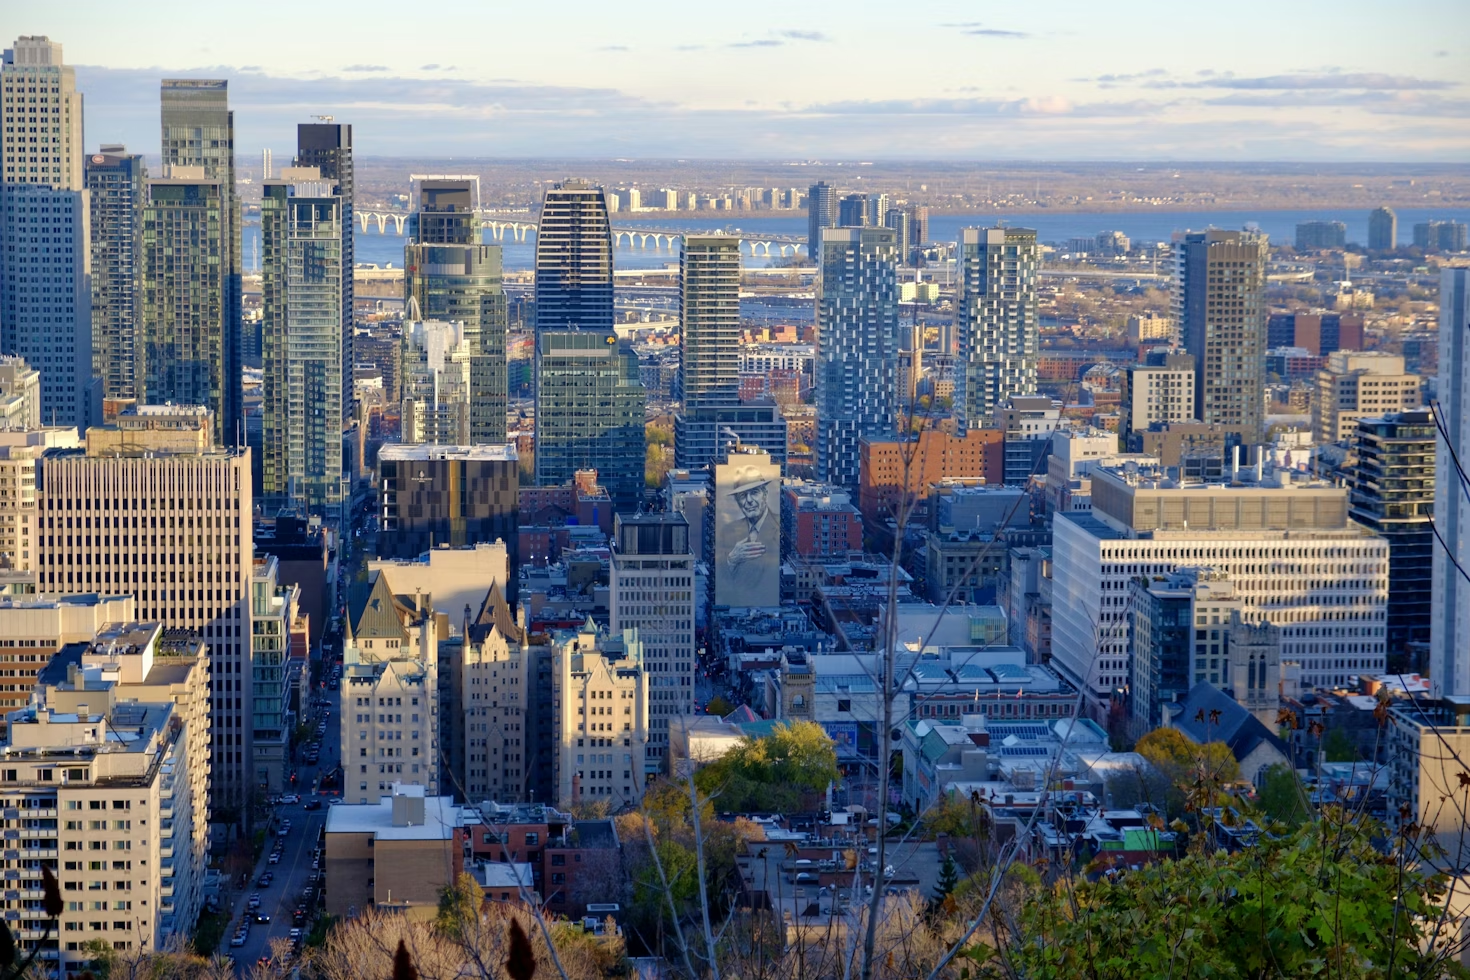
Montréal, QC
That does not solve Canada’s affordability problem. Rents remain high compared with pre-pandemic levels, and ownership costs are still stretched in many major markets. But it does change the near-term housing picture. For renters, new supply is creating more options in some markets. For would-be buyers, softer rents may reduce some of the pressure to purchase quickly. For investors, especially in condo-heavy markets, lower asking rents and higher vacancies can make the ownership math more difficult.
The May takeaway is that Canada’s housing market is recalibrating rather than rebounding quickly. Sales improved slightly in April, and prices are showing early signs of stabilization, but the expected resale recovery has been pushed further out. Price growth is likely to remain limited in several of the country’s largest markets, supply is giving buyers more leverage, and regional divides are becoming harder to smooth over with national averages.












