

New York, NY | Mihai_Andritoiu/Shutterstock.com
Inflation is cooling, mortgage rates have moved down from last year’s highs, and for-sale inventory is gradually improving in many markets—but closed sales remain soft. That combination has produced a housing market that feels less uniformly “hot” or “slow” and more deliberately sorted. Homes that are priced to today’s demand and present as low-risk decisions are still earning urgency. Listings that ask buyers to underwrite uncertainty—through aspirational pricing, deferred maintenance, or ambiguous renovation scope—are far more likely to stall.
The national data captures that push and pull. According to the National Association of REALTORS® (NAR), existing-home sales fell 8.4% in January to a seasonally adjusted annual rate of 3.91 million, with declines reported across the Northeast, West, Midwest, and South. Yet pricing has held: NAR put the national median existing-home price at $396,800, up 0.9% year over year. Inventory is also inching higher. NAR reported 1.22 million homes for sale at the end of January—about 3.7 months of supply—still below what most would call balanced, but meaningfully improved versus the tightest points of the past cycle. Together, those figures describe a market with more choice than last winter, but not enough supply to erase competition where value is clear.
San Francisco, CA
SUBSCRIBE TO THE HAVEN MAILING LIST
Curated homes, market intelligence and design stories — a few emails a month.
No spam. Unsubscribe any time.
Rates and inflation are reinforcing the month’s “steadier, not easy” tone. Freddie Mac’s Primary Mortgage Market Survey® put the average 30-year fixed rate at 6.01% as of February 19, keeping borrowing costs in the low-sixes range. Inflation has eased as well: the U.S. Bureau of Labor Statistics reported CPI up 2.4% over the 12 months ending January. These are constructive signals for sentiment, but they don’t reset affordability. In much of the country, the monthly payment remains the governing variable—and that reality is shaping how buyers judge pricing, condition, and risk.
More Inventory Is Changing Behavior
As options return, buyers are shopping differently. Realtor.com’s 2026 national forecast projects further gains in existing-home inventory after a meaningful increase in 2025, pointing to a market defined by side-by-side comparison rather than scarcity-driven impulse. That shift matters because it changes what “motivated” looks like. Many buyers are still engaged, but they are more willing to negotiate, pause, or walk away if the numbers—or the unknowns—don’t pencil. The homes that win are the ones that feel easiest to say yes to on day one. Jennifer Carey, Director of Sales at REAL New York, notes that buyer inquiries and showing requests picked up in her market as the post-holiday lull faded, with price-conscious shoppers moving faster when a home feels well priced and well presented.
Atlanta, GA
The Importance of Correct Pricing
In this environment, pricing does more than attract attention—it establishes credibility. The faster a listing earns buyer trust, the more likely it is to create momentum before hesitation sets in. In a high-cost, rate-sensitive market like New York City, Noah Freedman, co-founder of BOND New York, put it bluntly: “Correct pricing is what causes buyers to bid on properties, full stop.” While that perspective is grounded in one metro, the underlying mechanism is broadly national: buyers will stretch for an obvious value, but they are far less forgiving when pricing appears unmoored from recent comps.
Price adjustments can still work, but they often function as signals as much as solutions. In many markets, buyers monitor reductions as a cue that a seller is ready to deal—yet a late correction can also confirm what the market suspected from the start. The listings that move cleanly tend to be those that are positioned correctly at launch, not those that need the market to negotiate them into reality.
“Friction” Is the New Deal-Breaker
If pricing is the first filter, friction is the second. Friction is anything that forces a buyer to take a leap they can’t neatly quantify: a hazy renovation scope, unclear maintenance history, inspection uncertainty, or a home that looks like a project disguised as a finished product. In a payment-sensitive market, those unknowns feel heavier. Buyers don’t just ask, “Can I afford it?” They ask, “What might this cost me after I move in—and how confident am I about that number?” Lizette Sinhart, a licensed real estate salesperson with Christie’s International Real Estate Group in Westchester, notes that in her especially inventory-constrained pocket, a clean, well-structured offer is the key thing that moves the needle.
That’s why presentation has become more than aesthetics. Strong photography, clean staging, and straightforward disclosures reduce perceived risk and help a buyer understand what they’re paying for. Maxwell Taub, a licensed real estate salesperson at Keller Williams NYC, noted that visuals and pricing have to work together from the start: great photos can win attention, but unrealistic pricing will still stall momentum. Nationally, the logic is the same—when buyers can compare more homes, they punish listings that feel difficult to evaluate or easy to second-guess.
Seattle, WA
Condition Is Commanding a Premium—Unless Price Makes the Trade-off Irresistible
Across much of the country, “turnkey” is back to being a functional term, not a marketing adjective. Buyers who are already committing to a higher monthly payment are often reluctant to add immediate renovation costs and decision fatigue. “Buyers are showing through their actions that they don’t want to do work,” Freedman said, describing a preference for move-in-ready homes that don’t require mechanical, structural, or meaningful cosmetic repairs. In many markets, that preference is translating into a clear premium for homes that feel complete—and longer timelines for listings that imply an open-ended to-do list, unless the pricing makes that trade-off unmistakable.
There are exceptions that prove the rule. In some tight submarkets, pricing can overpower condition. In Brooklyn, Melissa Leifer, a licensed real estate salesperson at Keller Williams NYC, said even apartments needing gut renovations are now seeing multiple offers when they’re priced right. The takeaway is not that buyers suddenly love projects. It’s that friction is tolerable when value is clear—and intolerable when value is ambiguous.
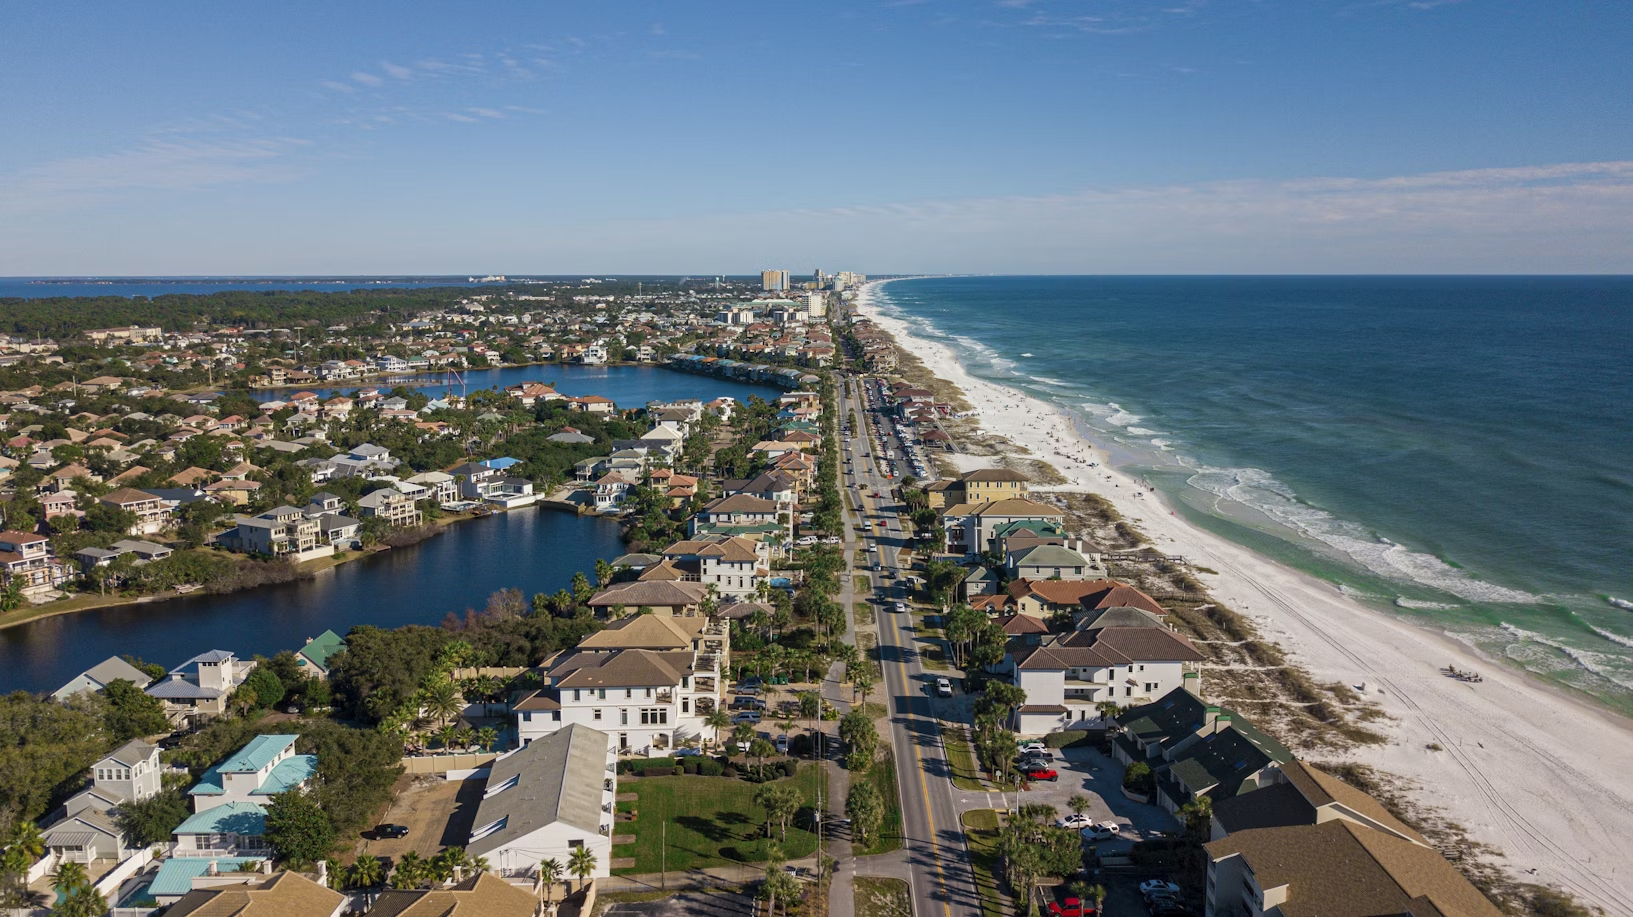
Destin, FL
Financing Strategy Is Returning Quietly, but Meaningfully
With rates steadier and inventory improving at the margins, deal structure is becoming more prominent again. Buyers and sellers are leaning on tools that support affordability without forcing an immediate price reset: rate buydowns, closing credits, and other concessions that lower the payment enough to move a decision from “not yet” to “now.” Leifer noted she is seeing more buydowns so far in 2026 than she saw across all of last year. These strategies can change timing—and timing increasingly matters in a market where buyers have more alternatives.
New Construction Remains Cautious
On the new-construction side, the tone is still measured. The NAHB/Wells Fargo Housing Market Index continues to reflect builder restraint, consistent with a climate where affordability remains the primary limiter even as inflation cools and rates stabilize. Incentives can help close the gap, but builders are still working within a cost structure that discourages aggressive expansion—while buyers remain sensitive to anything that pushes the payment higher.
Bottom Line
This is not a market defined by a single speed, but rather defined by selectivity. Fewer closings can coexist with resilient pricing when buyers are deliberate and inventory is only gradually loosening. For buyers, the environment offers more choice, steadier borrowing costs, and more room to negotiate in the right situations—but success is increasingly tied to discipline and clarity. For sellers, the playbook is simple and less forgiving than it was: price correctly from the start, present the home with minimal ambiguity, and reduce friction wherever possible, because today’s buyers are comparing everything—and moving quickly only when the value is unmistakable.












